Once authorities say it is safe to return, photograph flood damage before cleanup or disposal whenever you can do so safely. Notify your insurer promptly, make a room-by-room record of damaged property, save receipts and communications, and ask which deadlines and evidence requirements apply to your specific policy. NFIP guidance provides a useful process for its policyholders, but it is not a universal rulebook for private flood insurance.
Start with safety, then report the loss
Do not enter an unsafe building to get evidence
Wait until local authorities say it is safe to return. Floodwater can leave electrical and gas hazards behind. FloodSmart advises turning off electricity and gas before entering, having a qualified expert inspect the systems before power is restored, wearing protective equipment, and running portable generators outside and away from the home. Follow local emergency instructions and do not put yourself at risk to take photographs or retrieve belongings.
If conditions prevent you from documenting a room or item, prioritize safety. Make a note of what you could not safely photograph and tell the insurer. Necessary health-related cleanup may need to happen before a full inspection; document what you can first, but do not delay urgent action just to preserve evidence.
Contact the insurer promptly
Report the flood and apparent loss as soon as possible, even if you have not finished the inventory. Ask the representative to confirm:
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →#1 Best Overall
- 16MP Sensor: Captures detailed photos with a CMOS sensor for everyday shooting
- Optical Zoom: 4x optical zoom with a 27mm wide angle lens for flexible framing indoors or outdoors
- Full HD Video: Records 1080p video for travel clips, family moments, or simple vlogging
- Memory Support: Works with Class 10 SD, SDHC, or SDXC cards up to 512GB
- LCD Screen and Battery: 2.7in LCD screen with 2 AA alkaline batteries for convenient on-the-go use
- Whether the policy includes building coverage, contents coverage, or both.
- How to submit photographs, video, inventories, receipts, and other supporting records.
- Whether the insurer will arrange an inspection and what you should preserve until then.
- The deadlines that apply to this policy and this loss, including any proof-of-loss requirement.
- Which reasonable cleanup, temporary protection, or repair expenses may be covered, and what records the insurer needs.
Write down the answers and, when possible, ask for important instructions in writing. If you have private flood insurance, check your declarations and policy wording as well as the insurer’s instructions. Requirements can depend on the policy and applicable state or local rules; NFIP procedures should not be assumed to govern a private policy.
When you report the loss, record the date and time, the name and phone number of the person you spoke with, and any claim number you receive. Ask how the insurer wants documents labeled or grouped so that photos, inventory entries, and receipts can be matched to the claim. If you do not yet know the full extent of the damage, say so rather than delaying the initial report while you investigate every room.
Photograph and record the damage before cleanup
When it is safe and practical, document damaged areas before cleaning, moving, repairing, or throwing anything away. A phone that takes clear photographs and video is sufficient; NFIP guidance does not require a particular camera or app. Keep the original files, and avoid relying on edited or compressed copies as your only record.
Work from the wide view to the detail
- Start outside. Photograph the property and visible exterior damage, including affected foundations and other structural areas.
- Take a wide view of each affected room. Capture enough of the room to show where the damage is and how it relates to the rest of the space.
- Photograph close details. Record damage to floors, walls, ceilings, furnishings, appliances, and individual belongings. Take more than one angle if a single image does not show the condition clearly.
- Show water levels and water lines. Include visible marks and affected surfaces that help establish how high the water reached.
- Record identifying details. Photograph make, model, and serial-number labels on appliances and electronics when they are accessible and safe to reach.
- Use video as a supplement. A short walkthrough can help show the layout and relationship among damaged areas, but it should not replace still photographs of individual damage and identifying labels.
For each photograph or video, keep enough context to identify the room or item. A simple written note, such as “living room, north wall” or “kitchen refrigerator label,” can make the file easier to match to your inventory later. Preserve the original files and make a separate backup if you can.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Try to capture a sequence that tells a clear story: a wide room view, the affected area, then close detail of the damage or identifying label. If you photograph a water line, include enough of the surrounding wall or fixture to show where it is. Keep notes about rooms or areas you could not enter, and explain why they were inaccessible when you speak with the insurer or adjuster.
Evidence gathered before cleanup is generally more direct than trying to recreate the condition later. But an incomplete photo set is not a reason to delay necessary work. If cleanup or repairs must begin before you can photograph everything, preserve what evidence you safely can, note what changed and when, and contact the insurer about any missing documentation.
Document contents before they are moved or discarded
Photograph damaged property in place when possible, then take closer images of the item and any useful identification label. If an item must be moved for safety or cleanup, record its condition first when you can do so without delaying necessary action. For property that must be discarded because it is hazardous, spoiled, or moldy, take photographs before disposal if it is safe and practicable.
When photographing multiple similar belongings, take a group image for context and then make closer images that distinguish the items and show their condition. Add a note explaining what is included in a group photograph. Do not rely on a single room-wide image to establish the condition or identity of every individual item.
NFIP guidance describes covered flood damage as direct physical loss caused by flood. Its FAQ distinguishes water entering from the ground up from rain entering from above because of roof damage. The cause and policy terms matter, so record what you observed without trying to decide coverage yourself. Basement coverage under an NFIP policy is limited and depends on the coverage type and item; do not assume every basement loss is covered.
Build an itemized inventory tied to evidence
A useful inventory lets an adjuster identify what was damaged, where it was, and what supporting evidence you have. Make one entry per item or sensible group of similar items rather than using a vague total such as “clothes” or “kitchen goods.” The NFIP policyholder checklist recommends recording descriptions, values, identifiers, quantities, approximate age, and replacement cost value for contents.
Rank #2
- 16MP Sensor: Captures detailed photos with a CMOS sensor for everyday shooting
- Optical Zoom: 5x optical zoom with a 28mm wide angle lens for flexible framing indoors or outdoors
- Full HD Video: Records 1080p video for travel clips, family moments, or simple vlogging
- Memory Support: Works with Class 10 SD, SDHC, or SDXC cards up to 512GB
- Rechargeable Battery: Included LB-012 lithium-ion battery charges in the camera over USB with the supplied adapter in about 2 hours; charge it for at least 4 hours before first use to maximize battery life
Record these details for each damaged item
- Room or location and a clear description of the item.
- Quantity, if more than one item is involved.
- Approximate age and condition before the flood, to the extent you know them.
- Make, model, and serial number when available, especially for appliances and electronics.
- Estimated value or replacement cost, with the basis for the estimate if you have it.
- The photograph or video that shows the item and its damage.
- Any receipt, invoice, warranty, or other record that supports the description or value.
Do not invent a serial number, purchase date, or exact value you cannot establish. Mark estimates as estimates and note what supports them. If you no longer have a receipt, record the information you do know and gather other available records rather than leaving the item out.
Give each inventory entry a consistent label, such as a room name plus an item number, and use that same label in your photo notes or file names. For example, “Kitchen-03” can identify an entry and its related photos. This does not require a special app or format; the goal is to let you and the adjuster find the matching evidence without guessing.
Recommended Free Tools
Keep the value field distinct from a claim decision. An estimated replacement cost is information for the insurer to review, not a promise about what the policy will pay. If you are unsure of a value, say that it is an estimate and save the basis for it, such as a receipt, invoice, warranty, or other record you already have.
Keep building damage and contents organized
Keep structural damage—such as affected floors, walls, ceilings, or foundations—distinct from damaged belongings in your notes. This helps you compare the evidence with the parts of the policy the insurer says are in force. Whether an item is treated as building property or contents, and whether it is covered, depends on the actual policy and the item’s circumstances.
Update the inventory as you discover damage, but keep dated copies of earlier versions. If an item is removed or discarded, add a note about when and why. This creates a record of what changed without erasing the description you submitted earlier.
Building coverage and contents coverage are not interchangeable: confirm whether your policy includes one or both, then organize the evidence accordingly. Do not assume that a damaged fixture, appliance, or other item belongs in a particular category without checking the policy or asking the insurer how it should be listed.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Preserve evidence, receipts, and a communication file
Keep useful physical evidence and expense records
Separate damaged from undamaged property for inspection where possible. FloodSmart advises retaining small samples of materials such as carpet, flooring, drywall, or insulation when it is safe and practicable. Do not keep a sample if doing so would create a health or safety problem. Photograph materials before removal and note where each sample came from.
Keep receipts and invoices for cleanup, repairs, replacements, and other expenses related to the loss. Before authorizing work or paying a contractor, speak with the insurer about its requirements and which expenses may be covered. Protect undamaged property where practical, and record steps you take to prevent further loss.
If a contractor removes damaged material, ask for an itemized estimate or invoice and keep it with your photos and notes. Record what was removed, where it came from, and when the work took place. Do not postpone necessary health or safety work while waiting for an inspection; instead, document the condition before work if practicable and contact the insurer about how to preserve evidence.
Make one claim file and log every important contact
Store the following together, with backups where possible:
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteRank #3
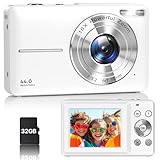
- Latest Digital Camera Built-in Fill Light : This compact digital camera is paired with a powerful CMOS processor and image stabilization to help you take & record the most exciting moments in 44 MP quality images & FHD 1080P quality videos anywhere, anytime. Plus, there is also a built-in fill light to help you take high quality pictures even in low light&dark settings, making this the perfect camera for all indoors/outdoors situations.
- Long-Lasting Battery Life & 16X Digital Zoom :This point and shoot camera will retain its battery charge even after long use. The controls and functions are easy to operate making this the perfect choice for children, teens and younger. This kids camera supports 16x digital zoom, you can zoom in or out the subject by pressing the W/T button for taking still photos to zoom in or out on distant objects and capture all the details you need.
- Multifunctional & Portable Digital Camera: This cheap digital camera is slim enough to fit in your pocket. You'll easily be able to take it with you on all your indoor/outdoor activities and adventures and ideal for beginners, children and teenagers. This kids digital camera is equipped with 20 filters, anti-shaking, self-timer, continuous shooting, date stamp, time-lapse recording, smile capture, internal MIC and speaker (recording sound videos), great for your daily photography needs.
- WEBCAM & PAUSE FUNCTION : More than just a FHD 1080p digital camera, it also works as a webcam for video calls and vlogging. Connect the camera to the computer, press shutter and power button at the same time and the camera will automatically turn on webcam mode for all your video calling and live streaming needs. The pause function allows you to pause when seeing playback videos.
- A Must Have Photography Device : This digital camera with SD card made from high-quality materials, this retro camera is safe and durable. Perfect for all ages to develop & improve their photographic abilities and observation skills. Our dedicated and experienced 24/7 support team is available for all after purchase troubleshooting, questions and technical help.
- Claim number and the insurer’s written instructions.
- Original photographs and videos, organized by date, room, or item.
- Current and earlier versions of your inventory.
- Estimates, contracts, invoices, receipts, and proof that you submitted documents.
- Emails and written messages with the insurer, adjuster, contractors, or cleanup workers.
For calls and conversations, note the date and time, the person’s name and phone number, what was discussed, any instructions or promises, and the next step. A communication log helps you track unanswered questions and recall what you were told without relying on memory.
Use the log to follow up on open questions, such as an inspection date, a document submission, or an explanation of a repair expense. Save the response with the related evidence. If you submit a file electronically or by another method, keep a dated copy or confirmation so you can show what you sent and when.
Prepare for the adjuster’s inspection
Arrange access with the insurer and have your photographs, inventory, receipts, and notes available. Walk the property with the adjuster when possible. Show the damage room by room, point out water lines and areas that were inaccessible or unsafe, and connect damaged items to the corresponding inventory entries and images.
For an NFIP claim, ask an adjuster to show identification and a Flood Control Number card. The adjuster documents the loss and submits a recommendation with supporting documentation; the insurer makes the claim decision. The adjuster’s estimate is therefore an important document to review, not itself a final coverage decision.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Before the visit, group or sort your evidence so you can quickly find the relevant photos, receipts, or inventory entry when a question comes up. Make a short list of damage you want to point out, including areas you could not safely enter earlier and damage discovered after the first round of photographs. Keep your own notes about what the adjuster inspected and any next steps discussed.
Ask what the estimate includes
When the estimate is available, compare it with your inventory and observed damage. Check whether rooms, structural areas, and individual items appear in the estimate and whether their descriptions match what you showed. Ask the insurer or adjuster to explain an item you do not understand. If you find an omission, an incorrect description, or additional damage, report it promptly and provide the related photographs, inventory entry, or other evidence.
Keep a copy of the estimate and your questions and responses. If damage becomes visible only after necessary work begins, document it before it is covered or removed when safe and practicable, then contact the insurer about how to submit the new evidence.
Do not treat the adjuster’s recommendation as the insurer’s final coverage decision. If the estimate and your records do not match, explain the specific difference in writing—for example, a room or item that appears to be missing—and attach the evidence that helps clarify it. Keep a copy of that communication in your claim file.
Understand the NFIP proof-of-loss timeframe
The NFIP policyholder checklist says to submit required documentation within 60 days of the flood or within the timeframe provided by the adjuster or insurer. FEMA/NFIP Claims Manual material from June 2025 summarizes the NFIP policy’s proof-of-loss requirement as 60 days, subject to program rules and possible waivers or extensions. Follow the instructions for your claim, submit early when possible, and ask the insurer in writing if you need clarification or additional time.
That 60-day guidance is NFIP-specific. It is not a blanket deadline for every private flood policy. For a private policy, ask the insurer which proof-of-loss and supporting-document deadlines control. Keep proof of what you sent and when, such as a submission confirmation or dated copy of your correspondence.
Rank #4
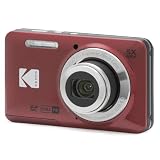
- 16MP Sensor: Captures detailed photos with a CMOS sensor for everyday shooting
- Optical Zoom: 5x optical zoom with a 28mm wide angle lens for flexible framing indoors or outdoors
- Full HD Video: Records 1080p video for travel clips, family moments, or simple vlogging
- Memory Support: Works with Class 10 SD, SDHC, or SDXC cards up to 512GB
- Rechargeable Battery: Included LB-012 lithium-ion battery charges in the camera over USB with the supplied adapter in about 2 hours; charge it for at least 4 hours before first use to maximize battery life
Ask what the insurer considers required documentation for your claim and whether it has given you a different timeframe. Do not assume that completing photographs or an inventory automatically satisfies a proof-of-loss requirement. If you need more time or discover additional damage, contact the insurer promptly and keep its response in writing.
Know what documentation can—and cannot—establish
Good records help show the condition and extent of damage, but they do not by themselves guarantee payment. Coverage depends on the policy terms and facts of the loss. NFIP guidance notes that standard NFIP policies do not cover mold damage, while its documentation guidance describes limited circumstances in which mold-related damage may be covered when authorities restrict access or floodwater makes entry unsafe. That is not a general promise of mold coverage; ask the insurer how the policy applies to your situation.
FloodSmart’s “How to start a flood insurance claim” page reports an average of $82,614 for all NFIP claims between 2020 and 2024, $87.5 billion paid in claims since 1978, and more than 2.7 million claims received; the page was accessed in 2026. These are program-wide figures, not a prediction or estimate for an individual claim.
Choose repair help carefully
If you need contractors, FloodSmart recommends getting multiple written estimates, checking licensing and insurance, checking references, and speaking with the insurer before signing a contract or paying. Keep estimates and agreements in your claim file, and do not assume that an estimate or proposed repair is automatically approved for coverage.
There is no special camera purchase required to document a claim. Clear images from a phone you already have can record the damage; the practical priorities are safety, coverage of all affected areas, and keeping the evidence organized.
Frequently Asked Questions
What should I photograph before flood cleanup?
When it is safe, take wide views of each affected room and the exterior, then close-ups of damaged floors, walls, ceilings, foundations, furnishings, appliances, and belongings. Photograph water lines and make, model, and serial-number labels on appliances or electronics when accessible. Video can supplement still photos, but should not replace them.
Free tools Windows power users keep installed
One-click scans. No signup required.
What should I include in a flood damage inventory?
For each damaged item, record its location and description, quantity, approximate age and prior condition, make/model/serial number when available, and estimated value or replacement cost. Match the entry to a photo or video and any receipt, invoice, warranty, or other supporting record. Mark uncertain values as estimates.
How do I prepare for my flood insurance inspection?
Have your inventory, photos, receipts, and notes ready, and walk through the property with the adjuster when possible. Point out water lines, damage, and areas that were inaccessible or unsafe. For an NFIP claim, ask the adjuster to show identification and a Flood Control Number card. Compare the estimate with your records and raise omissions or errors with the insurer.
How long do I have to submit my NFIP proof of loss?
NFIP checklist guidance says to submit required documentation within 60 days of the flood or within the timeframe the adjuster or insurer provides. FEMA/NFIP Claims Manual material from June 2025 summarizes a 60-day proof-of-loss requirement subject to program rules and possible waivers or extensions. Follow the instructions for your claim and ask the insurer in writing if you need clarification or more time. Private policies may have different deadlines.
Should I throw away flood-damaged belongings before the adjuster visits?
Photograph and document items before disposal whenever safe and practicable, and separate damaged from undamaged property for inspection where possible. Do not keep hazardous, spoiled, or moldy items if doing so creates a health risk or delays necessary cleanup. Tell the insurer what had to be removed and keep photos, notes, and related receipts.
The Bottom Line
Document flood damage only when it is safe: report the loss promptly, take wide and close photos before cleanup where practicable, build an itemized inventory tied to evidence, and keep receipts and a communication log. Review the adjuster’s estimate against your records, and confirm the actual deadlines and requirements with your insurer—NFIP’s 60-day guidance is not a universal rule for private policies.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.